A sales team can propose the same EUR 60 gift for three recipients and reach three different decisions. One recipient is a private-company customer after a completed project, another is evaluating an active tender, and the third works for a public body. A practical corporate gift policy for international companies must therefore consider recipient type, timing, purpose, local rules and the giver’s role—not value alone. Build one global control floor, add jurisdiction and business-unit annexes, and route each proposal to one of four outcomes: prohibit, pause for review, approve and record, or proceed under standard rules.
This article offers an operational model for marketing, procurement and programme owners. It is not legal advice. The applicable law, recipient organisation’s policy and your own counsel or compliance guidance take priority.
Start with the collision
Global gifting programmes tend to collide with local reality at the worst moment: a campaign is approved, stock is produced and a country team then discovers that one recipient group cannot accept it. The usual reaction is to search for a universal monetary threshold. That feels simple but leaves major risks untouched.
A modest gift can still be inappropriate during a tender, inspection, licence application, claim or contract negotiation. A higher-value item may be permitted in a carefully documented employee-recognition programme. Cash equivalents, personal delivery addresses, public officials, agents and accompanying hospitality can each change the analysis.
Policy should make these distinctions before someone selects products. It should also state that a recipient’s own employer may have stricter rules. An approved internal budget does not create permission for the recipient to accept the gift.
The UK government’s Bribery Act 2010 guidance explains procedures commercial organisations can put in place to prevent bribery, while the US Department of Justice and Securities and Exchange Commission maintain an updated FCPA Resource Guide. Neither source provides a universal safe gift value. The operational lesson is to design proportionate controls around context, risk and records instead of treating a number as automatic approval.
Build a global floor and local annexes
The global floor contains controls that apply everywhere. Local annexes explain where law, regulator expectations, business practice or a company’s risk appetite requires a different route.
| Policy layer | Global owner | Local or specialist owner | What it should decide |
|---|---|---|---|
| Purpose and prohibited conduct | Compliance or legal | Local counsel where required | Legitimate purpose, no intent to influence improperly, no concealment |
| Recipient classification | Programme owner | Local compliance or public-sector specialist | Private, public, state-owned, intermediary or other enhanced-risk category |
| Value and frequency | Finance/compliance | Country or business-unit owner | Calculation method, aggregation period and stricter local limits |
| Timing conflicts | Business owner | Tender, regulatory or account owner | Bids, negotiations, approvals, disputes and inspections |
| Product and delivery | Procurement | Local logistics or product specialist | Cash equivalents, restricted items, personal addresses and destination controls |
| Record and exception | Compliance operations | Named approver | Required evidence, retention and escalation path |
A local annex should be short enough to use. It can specify which recipients need enhanced review, which categories are prohibited, which approval tool applies and whom to contact. It should not repeat the whole global policy in slightly different words.
Policy version control matters as well. Record the effective date, owner, approver, review date and superseded version. If an annex changes while a programme is being prepared, identify which decision must be revisited. A folder of undated PDFs is not a control system.
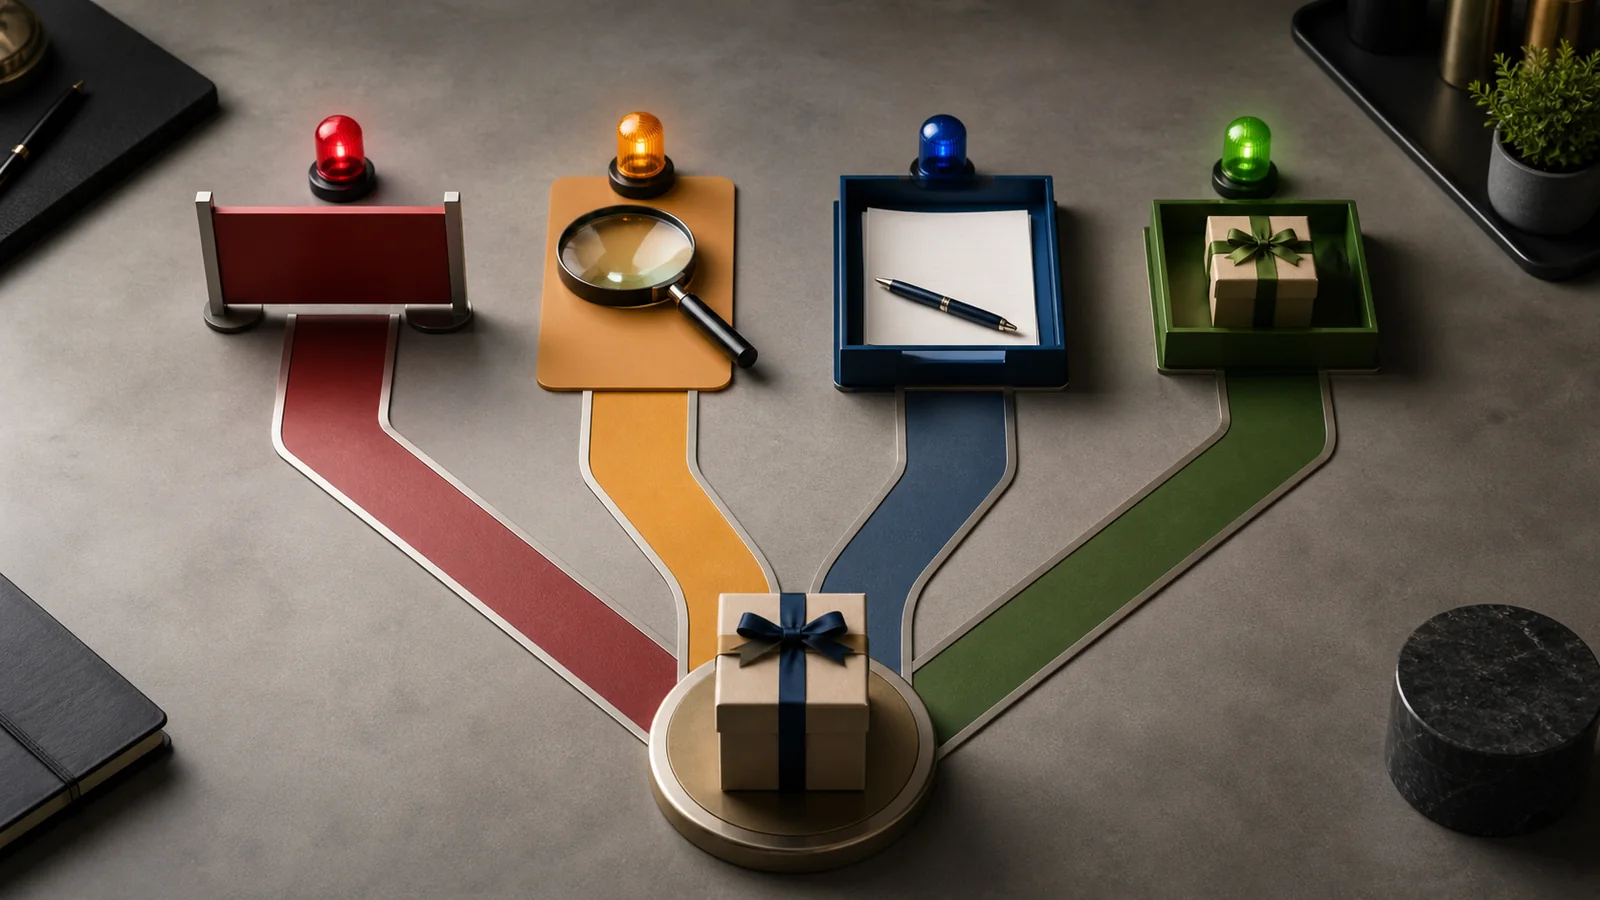
Route every proposal to one of four outcomes
Many policies explain what employees must not do but fail to show what happens next. Use four operational outcomes with clear evidence.
Prohibit
Stop the proposal when it involves cash or a prohibited equivalent, an improper purpose, concealment, a prohibited recipient or another non-negotiable rule. The programme should not search for a different description to make the same transfer appear acceptable.
Pause for review
Escalate when facts are incomplete or enhanced risk exists: a public-sector connection, active tender, intermediary, repeated gifts, unusual personal delivery, hospitality, a local-rule conflict or uncertainty about beneficial ownership. A pause is not a rejection. It protects the decision until the right owner has the facts.
Approve and record
Use explicit approval when policy permits the gift but requires a named approver, justification and record. Capture the exact item, fair value method, recipient organisation, timing, purpose and any conditions. “Marketing item” is not an adequate description if the package contains several components.
Proceed under standard rules
Low-risk proposals can proceed when every defined condition is met. Standard approval should still leave an auditable campaign record. The absence of individual review does not mean the activity disappears from reporting.
The US Department of Justice’s Evaluation of Corporate Compliance Programs asks how companies design, implement and apply compliance programmes in practice. Its broader context is enforcement evaluation, not gift-campaign instruction, but it reinforces a useful operating question: can the organisation show that the control works, is resourced and responds to what it learns?
Make the request record useful
The approval form should help an approver decide, not merely prove that a form was submitted. Collect the minimum complete set of facts:
- business purpose and campaign owner;
- recipient name or defined recipient group, organisation and classification;
- relationship status and any tender, negotiation or regulatory interaction;
- item description, quantity, unit value, total value and valuation basis;
- previous gifts or hospitality within the policy period;
- delivery route, country and whether a personal address is proposed;
- requested outcome, approver, decision, conditions and decision date.
Do not hide mixed packages behind the cheapest component. If a box contains merchandise, food and an experience voucher, record the complete transfer and apply the policy to each relevant category. Shipping and tax treatment may be accounted for separately, but the approval record should explain the valuation method consistently.
The record also needs a cancellation route. If a deal stage changes after approval or the recipient becomes connected to a public body, the programme owner must know who can place the delivery on hold. Approval is based on facts at a point in time, not a permanent entitlement.
Pressure-test a Q4 programme
A representative international software company plans 80 year-end gifts for customers in Germany, the United Kingdom and the United States. The initial list contains 68 established private-sector contacts, six prospects in active commercial evaluation, three employees of a state-owned enterprise, two external agents and one contact whose organisation prohibits gifts.
The programme does not force all 80 through one route. The prohibited recipient is removed. The six active prospects are paused until account and compliance owners assess timing. The state-owned-enterprise recipients receive enhanced review under the applicable annex. The agents are checked against intermediary controls. The remaining private-sector recipients can proceed only after frequency, value, purpose and recipient-policy checks are complete.
Procurement then discovers that twelve deliveries would go to personal addresses. That fact does not automatically make the gifts prohibited, but it changes the data and approval workflow. The team separates recipient-policy approval from consented address collection, limits data fields and sets a retention period. It also provides a no-gift alternative where a recipient cannot accept merchandise.
This pressure test happens before production. The campaign may still contain one visual concept, but the recipient list now carries decision status and fulfilment instructions. No pack is released because a country team assumes that another country’s approval applies.
Connect policy to procurement
Compliance approval should create usable procurement controls. Put the approved specification, recipient groups, maximum quantities, permitted substitutions and release conditions in the purchase brief. Require suppliers and fulfilment partners to stop exceptions rather than improvise.
For example, a fulfilment partner should not replace an unavailable non-cash item with a voucher unless that category has been approved. It should not send an unassigned package to a salesperson’s home for later distribution unless the delivery and custody route is authorised. It should not add a “complimentary” premium component that changes the value.
Budget approval also needs a separate lens. A client gift budget framework can define programme cost, contingency and cost per eligible recipient, but finance approval does not replace policy approval. Likewise, account-based marketing gifting can establish a relevant account purpose without proving that every recipient may accept the package.
Ask for a reconciliation after dispatch: approved recipients, released packs, failed deliveries, returns, substitutions, unused stock and exceptions. Reconcile the inventory to the decision record rather than treating fulfilment as the end of compliance.
Name the owner of the next decision
A policy becomes usable when an employee can answer three questions quickly: which rule applies, which outcome fits, and who owns the next decision? Publish a role map beside the policy. Programme teams describe purpose and recipients. Procurement controls specification and suppliers. Finance sets accounting rules. Compliance or legal owns the risk framework and escalations. Local specialists maintain annexes. Fulfilment releases only approved records.
Review the system using real exceptions. If country teams repeatedly ask the same question, improve the annex or form. If approvals arrive after production, move the gate earlier. If records cannot be reconciled to deliveries, connect the tools. If the policy blocks all modest, transparent appreciation because the route is too difficult, build a controlled standard path rather than encouraging workarounds.
The strongest corporate gift policy for international companies is not the one with the longest prohibited-items list. It is the one that turns context into a consistent decision before money, stock and recipient data are committed. LUGVO corporate gifting services can support the sourcing and fulfilment controls after a programme is approved; the services overview helps teams define the operational brief. Legal and compliance owners should remain responsible for the rules and exceptions that govern the programme.
 English
 Español
 Français
 العربية
 Italiano
 Deutsch
 日本語
 Nederlands
 Svenska
 Norsk bokmål
 Dansk
 Suomi
 한국어
 Ελληνικά
 עִבְרִית
 Română
 Türkçe
 Русский